Part I · Foundations and the four financial statements
The Language and Framework of Financial Reporting
لغة التقارير المالية وإطارها
You already know these ideas from your accounting studies in Arabic or French. What is new is the English names, the U.S. rules, and the exam wording.
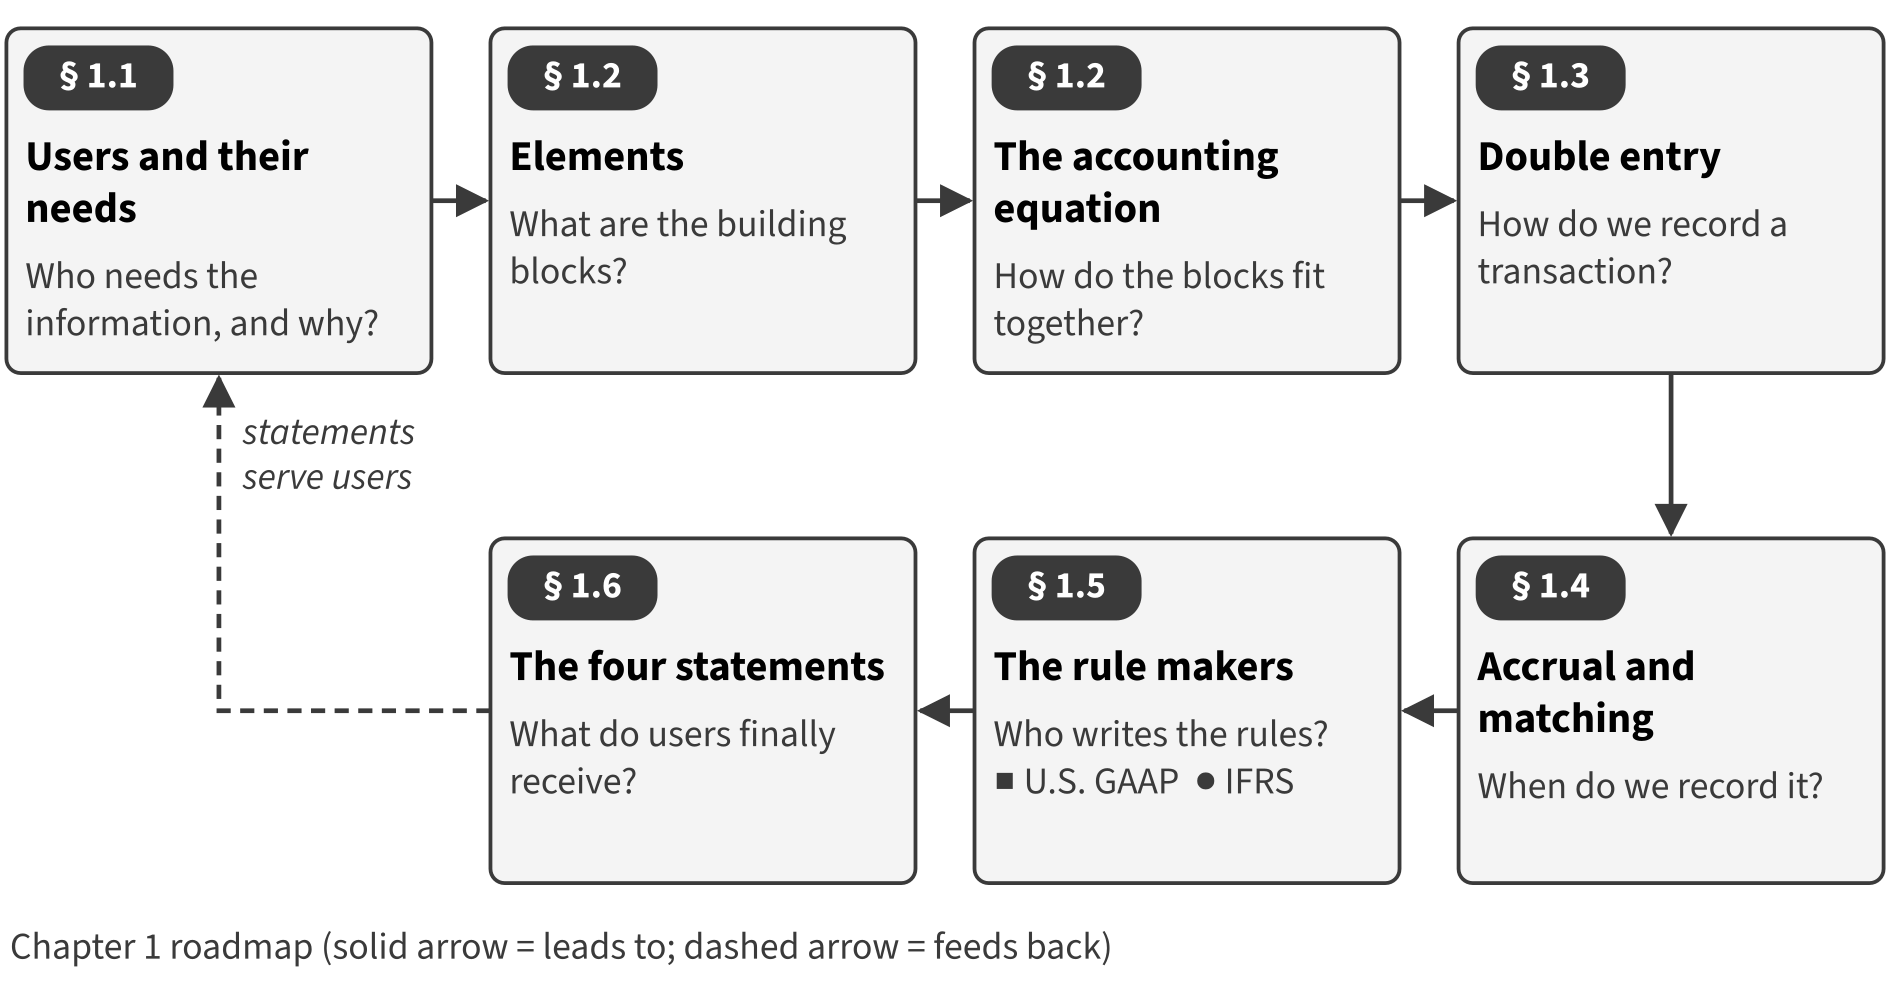
Start here
Then
What this chapter is tested on
| LOS | Official statement (ICMA, 2024) | In plain words | Depth here |
|---|---|---|---|
| A.1.a | identify the users of these financial statements and their needs | Identify the users of financial statements and what each user needs. | Full treatment |
| A.1.b | demonstrate an understanding of the purposes and uses of each statement | State what each of the four financial statements is for. | Overview — full in Ch. 2–5 |
| A.1.e | identify how various financial transactions affect the elements of each of the financial statements and determine the proper classification of a given transaction | Show how a transaction changes the accounting equation, and classify simple transactions. | Introduction — full in Ch. 2–5 |
| A.2.z | demonstrate an understanding of the matching principle with respect to revenues and expenses, and be able to apply it to a specific situation | Explain the accrual basis and the matching principle. | Introduction — full in Ch. 11 |
| Background | Background for this book (not an ICMA learning outcome). | Describe who sets U.S. GAAP and IFRS, and which rules the CMA exam uses. | Background |
Quoted from the ICMA Learning Outcome Statements effective September 1, 2024. The exam may test any outcome up to Level C.
The sixteen key terms
Every scene has Check Answers and Try Again. Try Again reshuffles rather than revealing. When you are wrong, the first thing you read is the reason for the option you chose, taken from the book's own explanations. Progress is saved in this browser.