Part I · Foundations and the four financial statements · Chapter 4
Equity and the Statement of Changes in Equity
حقوق الملكية وقائمة التغيرات في حقوق الملكية
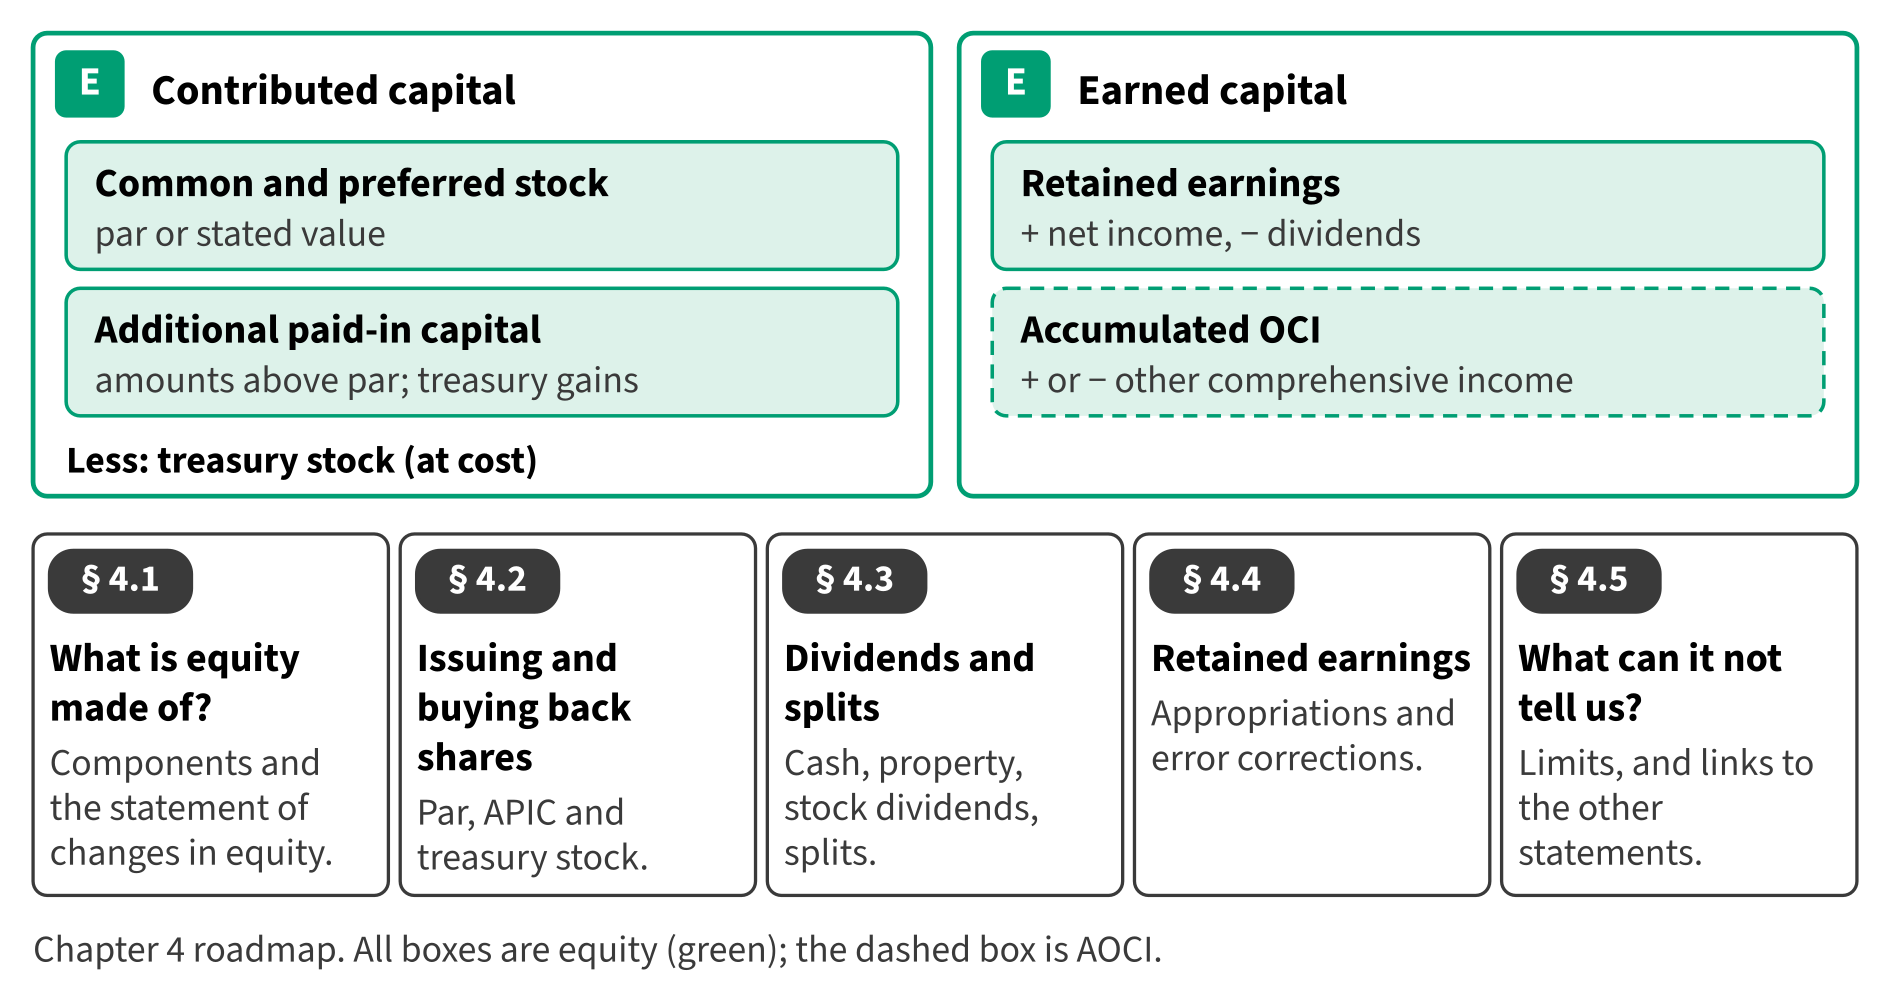
Chapters 2 and 3 showed where Orontes stands and how it performed. This chapter looks at the owners' part of the balance sheet. It explains how equity grows when owners invest and when the company earns profits, and how it falls when the company pays dividends or buys back its shares.
Start here
Then
What this chapter is tested on
| LOS | Official statement (ICMA, 2024) | In plain words | Depth here |
|---|---|---|---|
| A.1.b | demonstrate an understanding of the purposes and uses of each statement | Explain the purpose of the statement of changes in equity. | Full treatment (equity) |
| A.1.c | identify the major components and classifications of each statement | Identify the components of stockholders' equity and how each is presented. | Full treatment (equity) |
| A.2.v | identify transactions that affect paid-in capital and those that affect retained earnings | Identify transactions that affect paid-in capital and those that affect retained earnings, including treasury stock. | Full treatment |
| A.2.w | determine the effect on shareholders’ equity of large and small stock dividends, and stock splits | Determine the effects of cash, property and stock dividends and of stock splits. | Full treatment |
| A.1.g | demonstrate an understanding of how a balance sheet, an income statement, a statement of changes in equity, and a statement of cash flows (indirect method) are prepared | Prepare a statement of changes in equity. | Introduced (full in Chapter 5) |
| A.1.d | identify the limitations of each financial statement | Identify the limitations of reported equity. | Full treatment (equity) |
The official statements are quoted from the ICMA Learning Outcome Statements (effective September 1, 2024). The plain-words column restates them in simpler English. The exam may test any outcome up to Level C.
What you already know
Under IFRS you may have learned different names for the parts of equity, such as share capital and share premium. U.S. GAAP says common stock, additional paid-in capital, retained earnings and accumulated other comprehensive income. The False Friend box in Section 4.4 compares the words.
The 8 key terms
Every scene has Check Answers and Try Again. Try Again reshuffles rather than revealing. When you are wrong, the first thing you read is the reason for the option you chose, taken from the book's own explanations. Progress is saved in this browser.