Part III · Revenue, liabilities and income measurement · Chapter 15
Measuring Income: Gains, Losses, Comprehensive Income and Discontinued Operations
قياس الدخل: المكاسب والخسائر والدخل الشامل والعمليات غير المستمرة
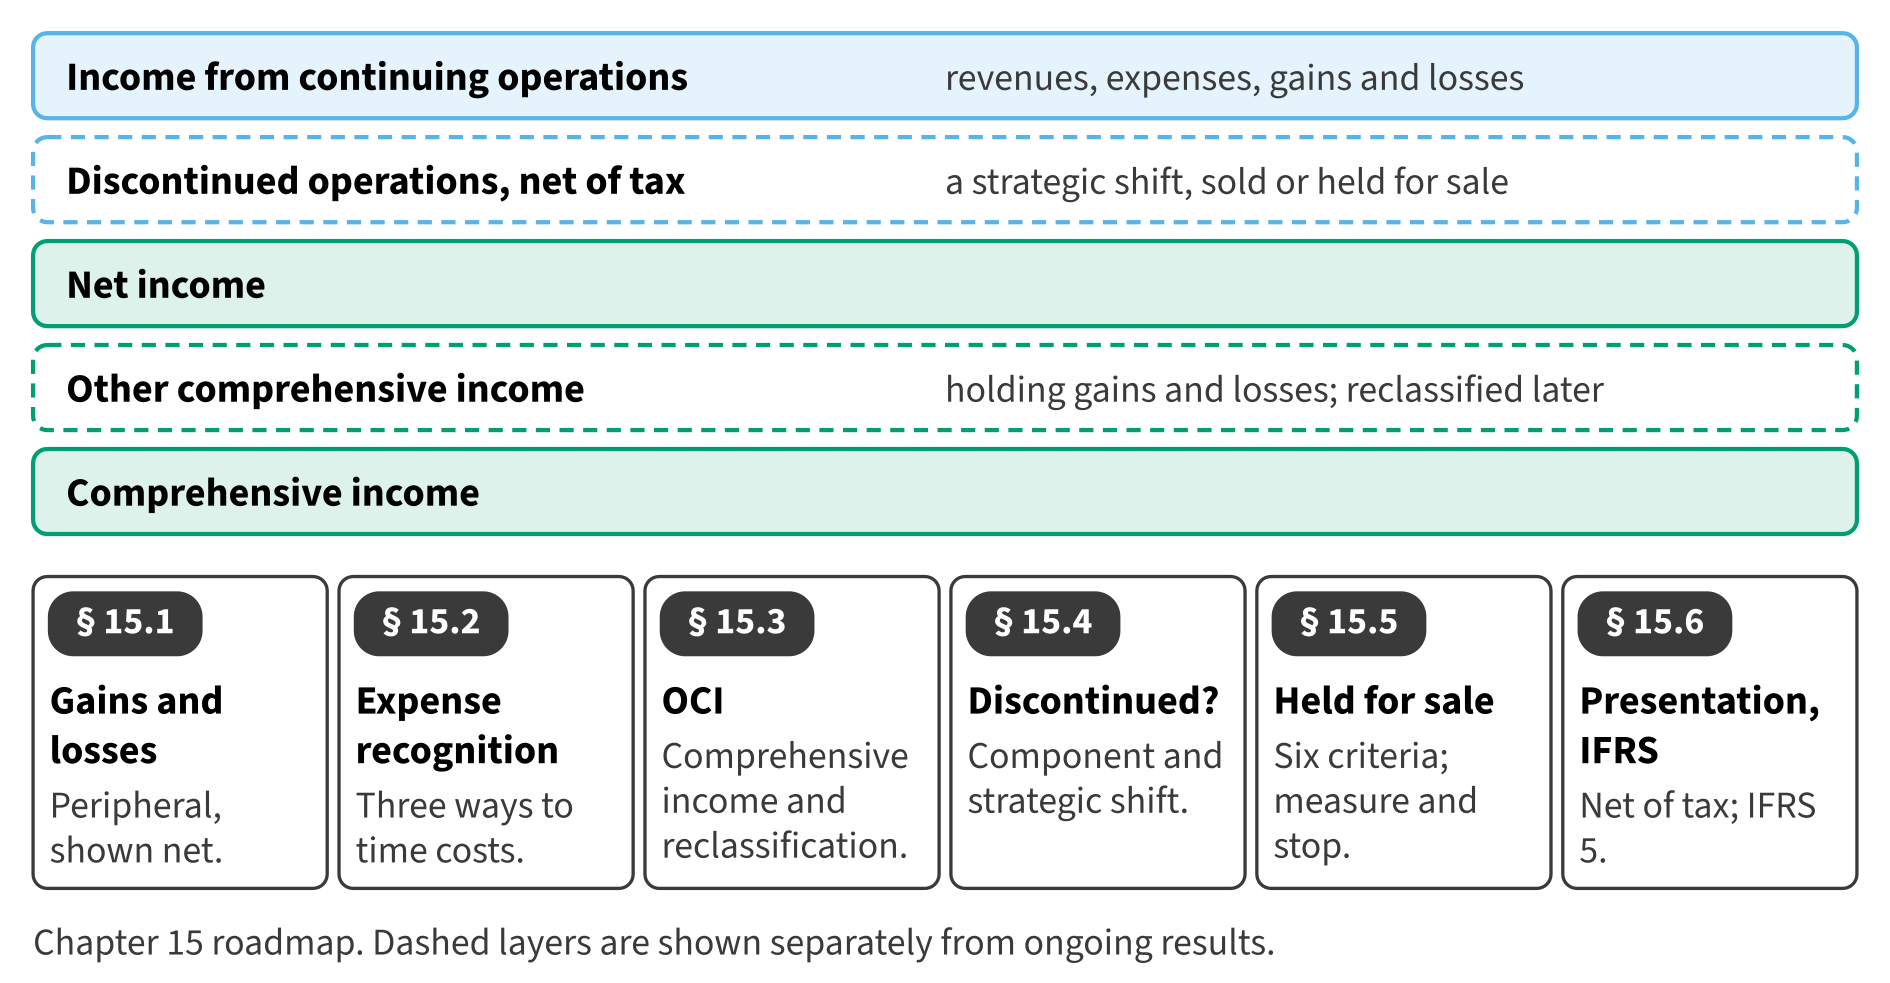
Chapter 3 introduced gains and losses, OCI and discontinued operations as parts of the income statement. This chapter gives the full rules behind them: how to measure each item, when to recognize it, and where to present it.
Start here
Then
What this chapter is tested on
| LOS | Official statement (ICMA, 2024) | In plain words | Depth here |
|---|---|---|---|
| A.2.aa | define gains and losses, and indicate the proper financial statement presentation for gains and losses | Define gains and losses and show where they are presented. | Full treatment |
| A.2.cc | demonstrate an understanding of expense recognition practices | Explain the three expense recognition practices. | Full treatment |
| A.2.dd | define and calculate comprehensive income | Define and calculate comprehensive income, including reclassification adjustments. | Full treatment |
| A.2.ee | identify the correct treatment of discontinued operations | Identify discontinued operations, apply the held-for-sale rules and present the results. | Full treatment |
| A.2.ff | identify and describe the following differences between U.S. GAAP and IFRS: (i) expense recognition, with respect to share-based payments and employee benefits; (ii) intangible assets, with respect to development costs and revaluation; (iii) inventories, with respect to costing methods, valuation, and write-downs (e.g., LIFO); (iv) leases, with respect to lessee operating and finance leases; (v) long-lived assets, with respect to revaluation, depreciation, and capitalization of borrowing costs; and (vi) impairment of assets, with respect to determination, calculation, and reversal of loss | Contrast IFRS 5 and IFRS OCI rules. | Preview (full in Chapter 17) |
The official statements are quoted from the ICMA Learning Outcome Statements (effective September 1, 2024). The plain-words column restates them in simpler English. The exam may test any outcome up to Level C.
What you already know
IFRS 5 has a similar idea of discontinued operations, and IFRS also has OCI. The tests and some presentation rules differ, and some IFRS OCI items never return to profit. Section 15.6 compares them.
The 8 key terms
Every scene has Check Answers and Try Again. Try Again reshuffles rather than revealing. When you are wrong, the first thing you read is the reason for the option you chose, taken from the book's own explanations. Progress is saved in this browser.