Part II · Measuring product cost · Chapter 10
Allocating Service Department Costs
توزيع تكاليف الأقسام الخدمية
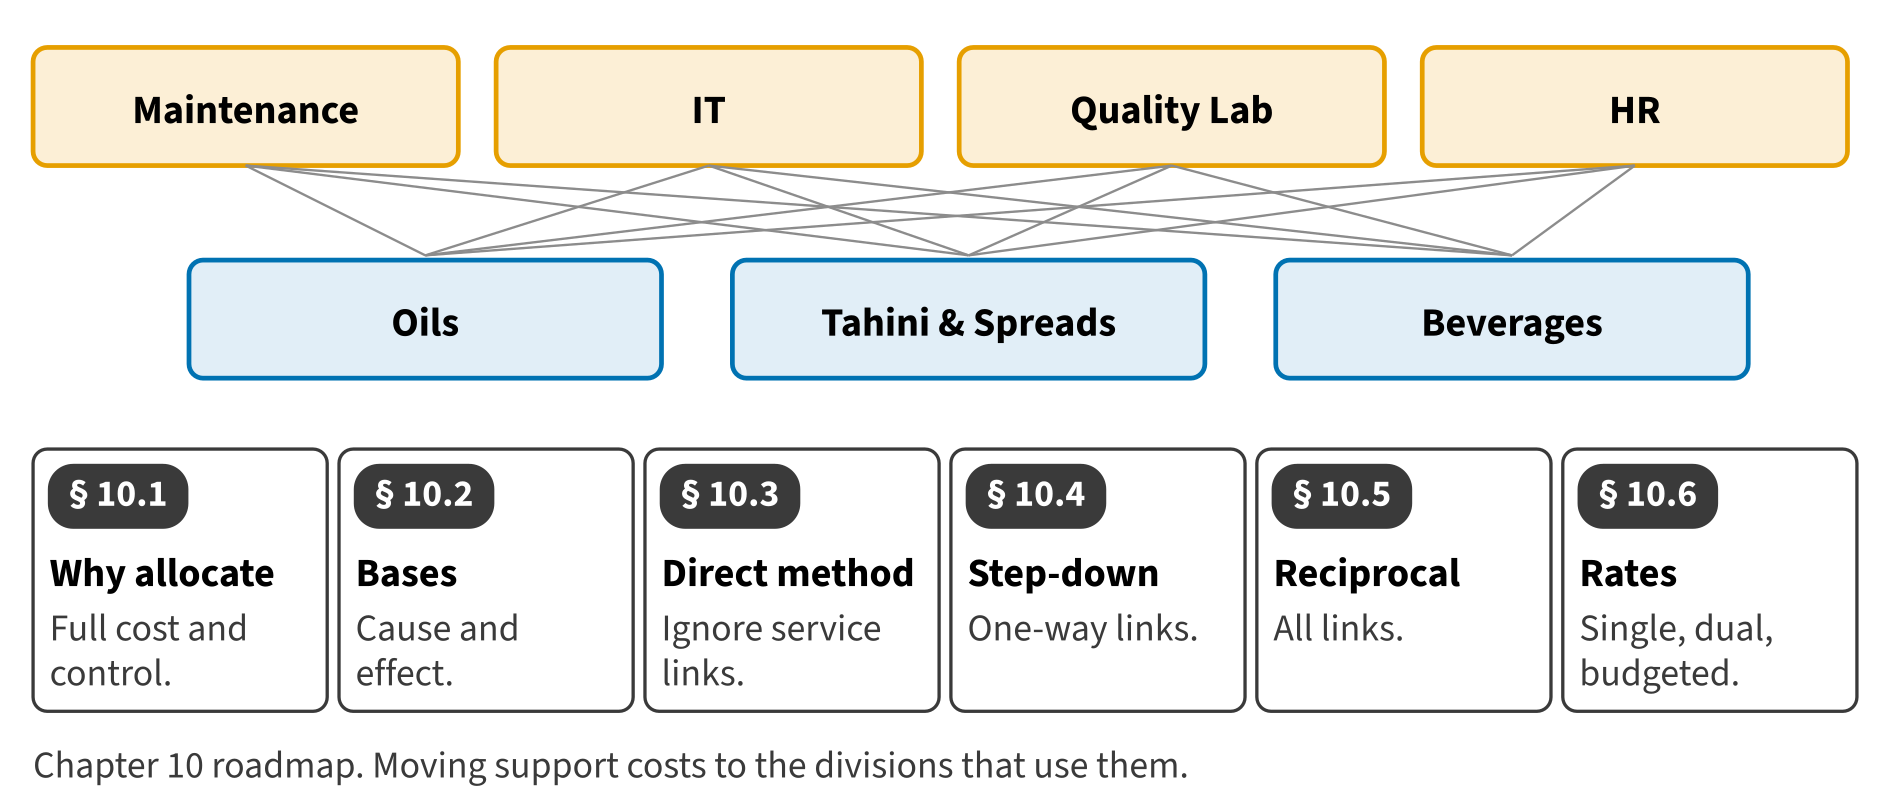
Every month since Chapter 5, each division's overhead has included a line called service department charges. In the Chapter 6 journal, Tahini & Spreads was charged $57,500 for March. Where does that number come from, and is it fair? This chapter answers both questions.
Start here
Then
What this chapter is tested on
| LOS | Official statement (ICMA, 2024) | In plain words | Depth here |
|---|---|---|---|
| D.3.o | explain why companies allocate the cost of service departments such as human resources or information technology to divisions, departments, or activities | Explain why service department costs are allocated, the choice of bases, and single, dual and budgeted rates. | Full treatment |
| D.3.p | calculate service or support department cost allocations using the direct method, the reciprocal method, the step-down method, and the dual allocation method | Calculate service department cost allocations with the direct, step-down and reciprocal methods. | Full treatment + Extended Example |
The official statements are quoted from the ICMA Learning Outcome Statements (effective September 1, 2024). The plain-words column restates them in simpler English. The exam may test any outcome up to Level C.
What you already know
Chapter 1 introduced cost pools and allocation bases. Chapter 8 put the divisions' service charges into their fixed overhead. This chapter shows where those charges come from.
The 8 key terms
Every scene has Check Answers and Try Again. Try Again reshuffles rather than revealing. When you are wrong, the first thing you read is the reason for the option you chose, taken from the book's own explanations. Progress is saved in this browser.