Part III · Measuring and managing performance · Chapter 16
Transfer Pricing
التسعير التحويلي
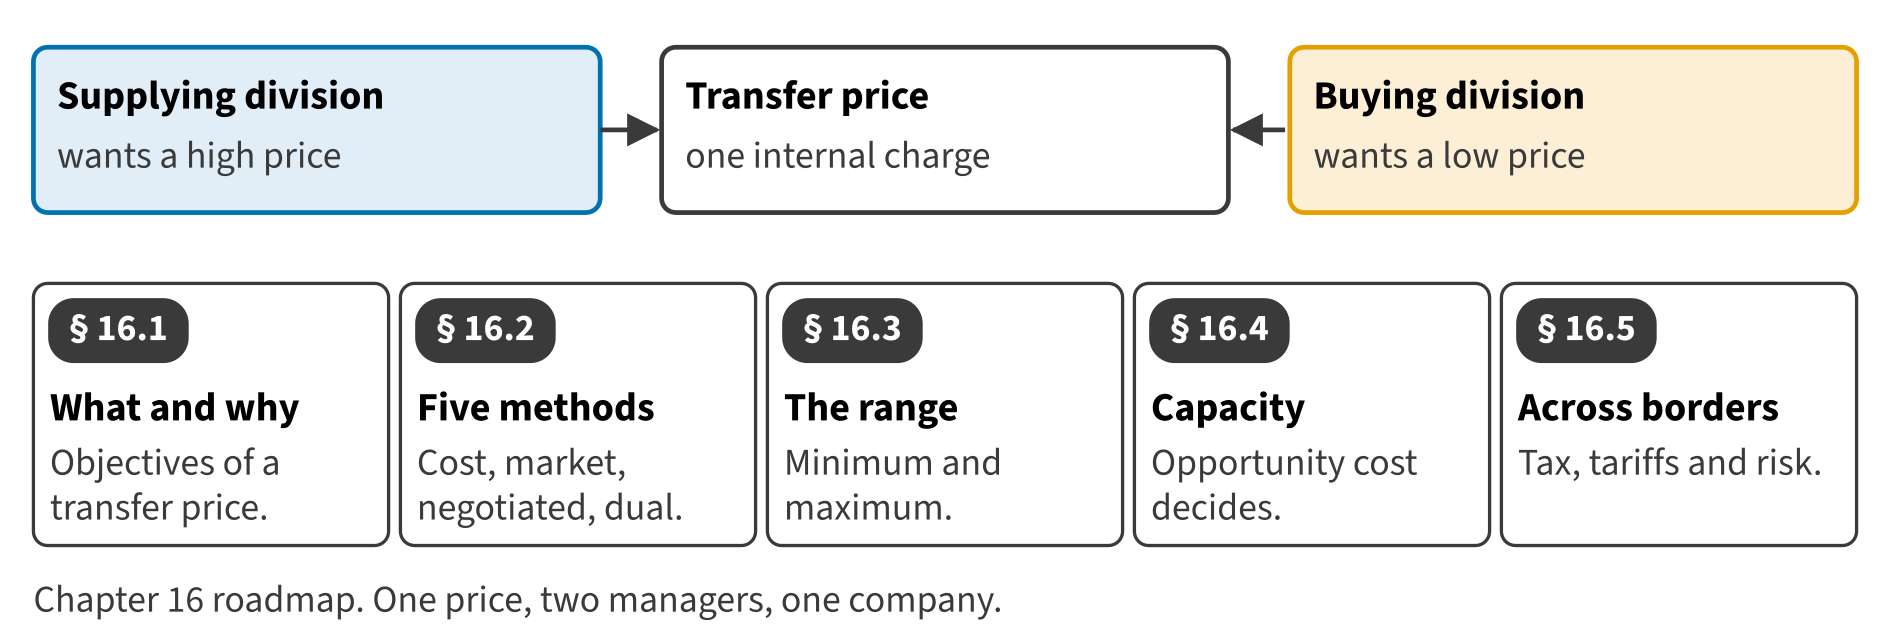
Levant Distribution delivers every case of juice that Beverages sells. Both are part of Orontes, so the price Levant charges Beverages is an internal matter: it moves profit from one division to the other and changes nothing for the company. Yet it changes how each manager behaves, and the wrong price can lead a manager to a decision that costs the company money.
Start here
Then
What this chapter is tested on
| LOS | Official statement (ICMA, 2024) | In plain words | Depth here |
|---|---|---|---|
| C.2.h | define transfer pricing and identify the objectives of transfer pricing | Define transfer pricing and identify the objectives of a transfer price. | Full treatment |
| C.2.i | identify the methods for determining transfer prices, and list and explain the advantages and disadvantages of each method | Identify the methods of setting transfer prices and explain the advantages and disadvantages of each. | Full treatment |
| C.2.j | calculate transfer prices using variable cost, full cost, market price, negotiated price, and dual-rate pricing | Calculate transfer prices using variable cost, full cost, market price, a negotiated price and dual rates. | Full treatment |
| C.2.k | explain how transfer pricing is affected by business issues, such as the presence of outside suppliers and the opportunity costs associated with capacity usage | Explain how outside suppliers and the opportunity cost of capacity affect the transfer price. | Full treatment |
| C.2.l | describe how special issues such as tariffs, exchange rates, taxes, currency restrictions, expropriation risk, and the availability of materials and skills affect performance evaluation in multinational companies | Describe how tariffs, exchange rates, taxes, currency restrictions, expropriation risk and the availability of materials and skills affect transfer pricing. | Full treatment + Extended Example |
The official statements are quoted from the ICMA Learning Outcome Statements (effective September 1, 2024). The plain-words column restates them in simpler English. The exam may test any outcome up to Level C.
What you already know
Chapter 15 made Levant a profit center and Beverages an investment center, which is why the price between them matters. Book 2, Chapter 17 compared making a part inside with buying it outside, using the same idea of avoidable cost.
The 8 key terms
Every scene has Check Answers and Try Again. Try Again reshuffles rather than revealing. When you are wrong, the first thing you read is the reason for the option you chose, taken from the book's own explanations. Progress is saved in this browser.