Part III · Measuring and managing performance · Chapter 17
Return on Investment, Residual Income and Measurement Issues
العائد على الاستثمار والدخل المتبقي وقضايا القياس
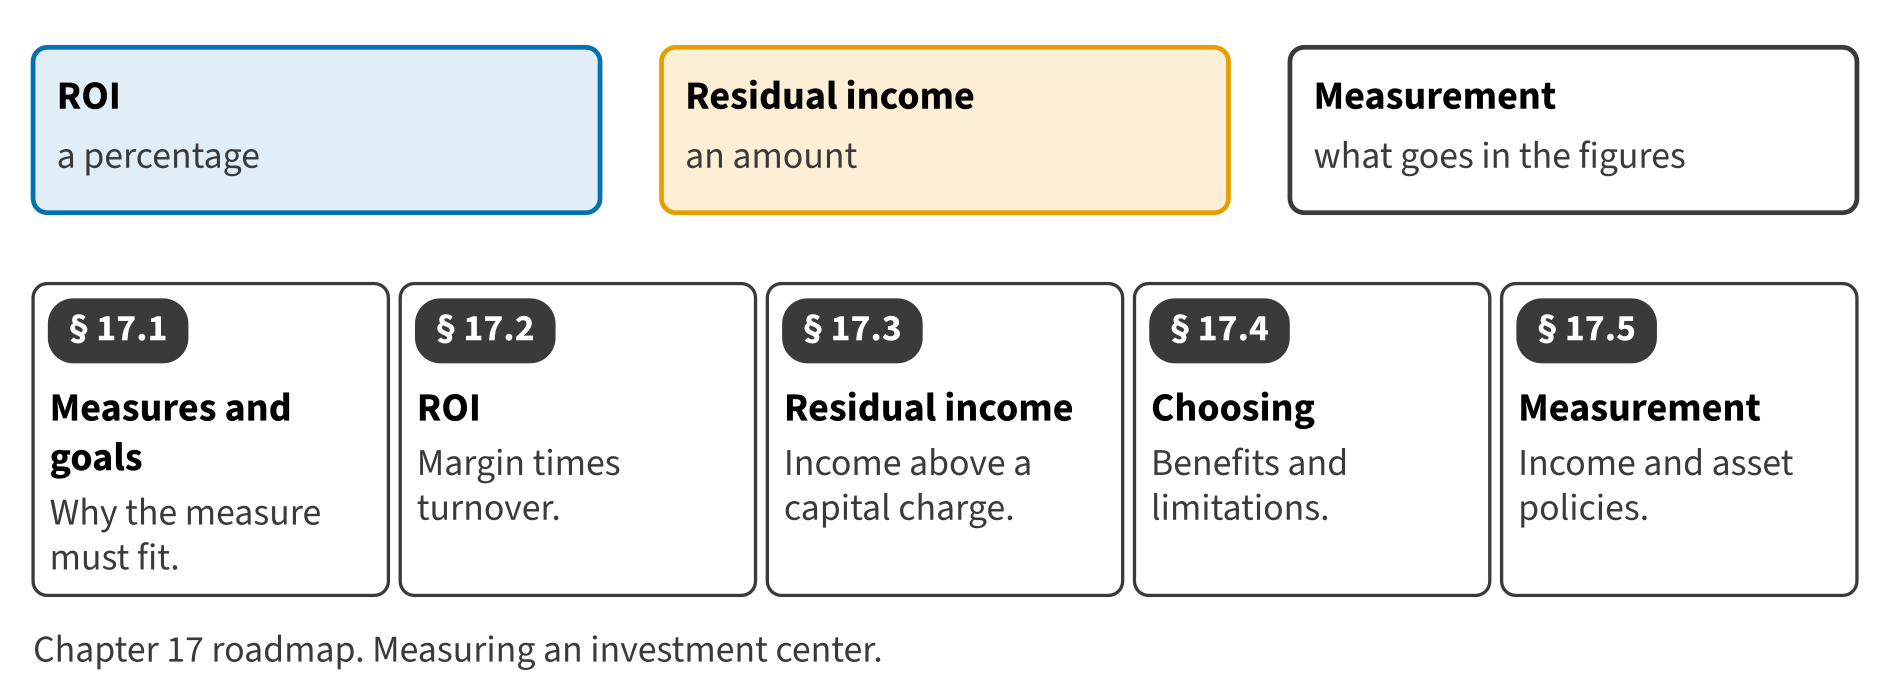
Chapter 15 made the Beverages division an investment center, which means its manager answers for profit and for the assets used to earn it. One number must therefore combine the two. This chapter builds that number two ways, shows where each one misleads, and ends with the accounting policies that quietly change both.
Start here
Then
What this chapter is tested on
| LOS | Official statement (ICMA, 2024) | In plain words | Depth here |
|---|---|---|---|
| C.3.a | explain why performance evaluation measures should be directly related to strategic and operational goals and objectives, why timely feedback is critical, and why performance measures should be related to the factors that drive the element being measured (e.g., cost drivers and revenue drivers) | Explain why performance measures should follow the strategic and operational goals, and why feedback must be timely. | Full treatment |
| C.3.e | define and calculate ROI | Define and calculate return on investment. | Full treatment |
| C.3.f | analyze and interpret ROI calculations | Analyse and interpret an ROI calculation. | Full treatment |
| C.3.g | define and calculate residual income (RI) | Define and calculate residual income. | Full treatment |
| C.3.h | analyze and interpret RI calculations | Analyse and interpret a residual income calculation. | Full treatment + Extended Example |
| C.3.i | compare the benefits and limitations of ROI and RI as measures of performance and explain their appropriate usage | Compare the benefits and limitations of ROI and residual income and explain when each is appropriate. | Full treatment + Extended Example |
| C.3.j | explain how revenue and expense recognition policies may affect the measurement of income and reduce comparability among business units | Explain how revenue and expense recognition policies affect measured income and reduce comparability. | Full treatment |
| C.3.k | explain how inventory measurement policies, joint asset sharing, and overall asset measurement policies may affect the measurement of investment and reduce comparability among business units | Explain how inventory measurement, shared assets and asset measurement policies affect the investment base. | Full treatment |
The official statements are quoted from the ICMA Learning Outcome Statements (effective September 1, 2024). The plain-words column restates them in simpler English. The exam may test any outcome up to Level C.
What you already know
Chapter 15 produced the segment margins used here. Chapter 1 set the group's return objective, and Chapter 10 tested the plan against it.
The 8 key terms
Every scene has Check Answers and Try Again. Try Again reshuffles rather than revealing. When you are wrong, the first thing you read is the reason for the option you chose, taken from the book's own explanations. Progress is saved in this browser.